
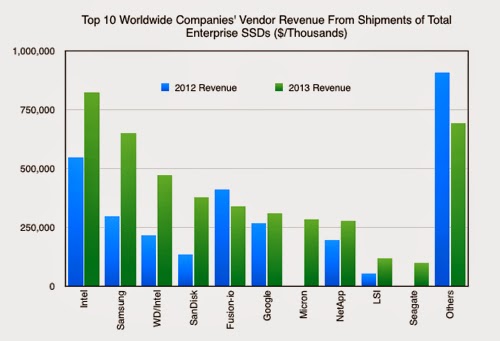
A recent survey by Gartner (see below) shows Intel and Samsung leading in shipment of SSD storage for enterprise.
Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com/
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com/
Gartner AFA data hits the street
By Chris Mellor, 13 Jun 2014
No,
it isn’t the greatly anticipated all-flash array magic quadrant, but it's great
Gartner analysis nonetheless. The number-crunchers at Gartner HWQ have produced
a Market Share Analysis: SSDs and Solid-State Arrays, Worldwide, 2013. Yummy.
Let’s see what’s inside.
The
doc, available as a download from Pure Storage (guess who's
done well in the analysis) after registering a few details. It looks at both
SSDs and all-flash arrays, which Gartner calls Solid State Arrays (SSAs) and
IBM comes out as the leading SSA shipper – with Pure Storage second.
SSAs
are defined carefully: ”SSAs are scalable, dedicated, solutions based solely on
solid-state semiconductor technology for data storage that cannot be configured
with HDD technology at any time. As distinct from SSD-only racks within ECB
storage arrays, an SSA must be a stand-alone product denoted with a specific
name and model number, which typically (but not always) includes an operating
system and data management software optimised for solid-state technology.”
To
cut a long story short, Dell and HDS all-flash array products are excluded, as
are all-flash versions of – for example – EMC VMAX and VNX, and NetApp FAS
arrays.
The
SSD category embraces PCIe flash cards and also includes “self-contained
solid-state NAND dual in-line memory modules (DIMMs), which must be used in dedicated
slots in servers. Mainstream PC SSDs being used in servers are counted in this
category due to end consumption.”
We’ll
graph the information here, and you can read the detailed numbers by
downloading the doc. The SSD info starts with worldwide vendor revenues:

Click chart for larger version
Total
SSD revenues in 2012 were $7.2 billion, and in 2013 had risen to $10.99
billion, a 53.1 per cent increase.
Samsung
as top dog got most of that with Intel, growing less, at number 2. Look at
Sandisk’s rocketing growth up into the no 3 slot, closely followed by Micron.
Toshiba held its fifth place but didn’t grow much. WD grew, Fusion-io declined
and now we’re in the tail-enders.
Now
let’s look at the enterprise SSD market:
Intel
is top dog, not second-placed Samsung. WD, with its HGST/Intel SSDs is in third
place followed by SanDisk successfully exhibiting its enterprise supplier
credentials. Then there’s Fusion-io, which declined 2012 - 2013, Google with
its internal use - amazing - Micron is a, we think, in a disappointing sixth
place, NetApp a, for it, strong seventh then LSI and Seagate. EMC does not
appear at all.
Now
for the SSA numbers.
Here
are the vendor revenue market share numbers:

Click chart to make it larger.
And
here the actual SSA revenues by vendor:

Click chart to make it larger
IBM
has had a wildly successful 2013 year, solidly overtaking Violin Memory to
claim a dominating number 1 slot. Pure Storage has rocketed to the number 2
position in 2013 while Violin Memory slumped from first place in 2013 to third
in 2013, illustrating the new management team’s uphill task. EMC has sprung
into fourth place from a standing start and NetApp is not far behind in the
fifth slot. Then there’s Nimbus Data and tail-ender Cisco - a dismal showing
for the networking behemoth in our view, with startup SolidFire very close
behind.
The
SSA market was sized by Gartner at $236.5m in 2012, and 182.1 per cent higher
at $667.3m in 2013. IBM’s SSA revenues grew at 278.1 per cent, Pure's at a
magnificent 642.3 per cent and no other vendor outpaced the market, meaning
they lost share.
Now
this is artificial, as EMC, Kaminario, SolidFire and HP had no presence in
Gartner’s numbers in 2013, but we can assert that Violin Memory, NetApp, Nimbus
and Cisco all lost share from 2012 to 2013. With EMC, Kaminario, SolidFire and
HP now in the SAA market we might expect these losses to continue in 2014.
The
Gartner analysis contains more data, segment metrics and so forth. It’s worth a
download and read if you’re interested.
Main takeaway? Big Blue
really is big in SSAs, Pure Storage is living up to its hype, and the SSA
market is growing at a fast lick. NAND the story goes on
