Thursday, December 11, 2014

Semiconductor Manufacturing 2015 Demand

Key new drivers for new semiconductor fabrication tools is advancing FinFETs 20nm to 16nm/14nm with reasonable yield, and the pace of implementation of 3D NAND. 

Ramp up of 3D flash manufacturing tools will really happen only in 2016 due to length of the development cycle.


In lithography, multi-patterning will continue to be used while EUV continue to faces difficulties. More details are below.


Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com/


Fab Tool Biz Faces Challenges In 2015

After a slight downturn in 2013, the semiconductor equipment industry rebounded and experienced a solid upturn in 2014. The recovery was primarily driven by tool spending in the foundry and DRAM [KC]sectors.
Another big and ongoing story continued to unfold in 2014. In late 2013, Applied Materials announced a definitive agreement to acquire Tokyo Electron Ltd. (TEL) for $9.3 billion. The deal was supposed to close in the second half of 2014. But now, the completion of the deal has been pushed out into 2015 amid a host of complicated regulatory issues.
In fact, the fate of the Applied-TEL deal is just one of the many burning issues for the industry in 2015. The other issues are also clear:
• Will IC-equipment vendors see an upturn or a downturn in 2015?
• What are the drivers?
• Will 450mm fabs, EUV [] and 2.5D [KC]/3D IC [KC] stacked die really happen?
• Will the equipment industry continue to see more acquisition activity in 2015?
The industry continues to consolidate and for good reason. At each node, there are simply fewer customers to serve in a maturing market. “More industry consolidation is needed in several areas, notably in process control and in the components/consumables market, where companies like MKS Instruments, Entegris and others participate,” said Patrick Ho, an analyst at Stifel Nicolaus. “So, will we see (acquisition activity) in 2015? There is a greater likelihood that the smaller players may combine with one another, versus any of the large players taking out the small players. My rationale: the big players are either busy, such as Applied and TEL, or content in their current positions for now. Longer term, we still need one more big deal to occur to further consolidate the space.”
Bold predictions
It’s difficult to predict the future, but there are signs that the Applied-TEL deal will get completed in 2015. So far, the deal has been approved by regulatory bodies in some countries, but not in others. “The deal gets done at some point,” Ho said. “Any deal of this size and scope, particularly when you’re dealing with a relatively consolidated customer base, will likely garner more scrutiny and even some pushbacks from customers. But like many other large deals, I believe ultimately it gets done with perhaps a few contingencies added on to the final deal.”
Another lingering issue is the IC-equipment forecast for 2015. There are mixed signals in the market. Economic growth remains sluggish in many countries. The worldwide geopolitical landscape is troubling. And in the electronics market, the two main catalysts for growth—smartphones and tablets—are showing signs of a slowdown.
As a result, the outlook is cloudy for tool vendors. In fact, citing the slowdown in mobile products and other factors, some are already lowering their forecasts for 2015. In its latest forecast, Gartner projected that semiconductor capital spending and the wafer fab equipment (WFE) market would grow by 11.4% and 17.1%, respectively, in 2014.
For 2015, Gartner currently predicts that semiconductor capital spending and WFE will grow by 8.8% and 11.1%, respectively. “At the moment, those numbers will probably come down a bit, as 2015 does not appear as robust as it did three months ago,” said Dean Freeman, an analyst with Gartner. “WFE for 2015 will be in the 5% to 10% range and CapEx will be closer to 5%. Much of this is dependent upon how much Samsung spends in Q4.”
Many other analysts have a similar forecast for 2015. But on the down side, the ATE market faces a possible downturn in 2015.
Drivers—DRAM, finFETs and NAND
Looking beyond the numbers, tool vendors are in the midst of the most challenging period in the industry’s history. Chipmakers are making a major transition from planar structures to various 3D-like architectures, such as 3D NAND, finFETs [KC] and stacked die.
Toolmakers, in turn, must develop new and advanced systems to meet customer requirements. But the cost to develop new tools is soaring out of control. And yet, there are fewer leading-edge customers at each node.
On the other hand, the shift towards new chip architectures are becoming the “inflection points”—or engines for growth–in the equipment industry, said Doug Bettinger, executive vice president and chief financial officer at Lam Research [], at a recent conference. “(The inflection points include) the move towards multi-patterning. That’s an enormous driver of growth,” Bettinger said. “It’s also the move to finFET from planar. It’s planar to 3D NAND, as well as the move to 3D packaging.”
In 2015, the big driver for fab tool orders will likely reside in the foundry segment, where GlobalFoundries [], Samsung and TSMC [] are making a transition from planar transistors at 20nm to finFETs at 16nm/14nm. Intel Corp. []is already ramping up its second-generation finFETs at 14nm.
For the foundry segment alone, WFE is expected to grow 5% to 10% in 2015, according to Stifel Nicolaus’ Ho. But tool orders for the finFET ramps are also somewhat dependent on one major factor—yield. The foundries, including Intel, are struggling with finFET yields. “With finFET, it will be a question of the magnitude of spending related to yields,” Ho said.
For DRAM, WFE is expected to grow 10% to 15% in 2015. And in NAND, WFE is projected to grow 5% to 10%, according to Stifel Nicolaus. In fact, the DRAM [KC] market remains strong. There could be a shortage of 2D NAND capacity in 2015. But with the exception of Samsung, vendors continue to push out their 3D NAND ramps.
“The timing of 3D NAND has been pushed out due to yields and demand, but the NAND flash industry will eventually transition to this technology,” Ho said. “The cost basis for planar NAND is still more attractive, so I believe the players will try and take advantage of this for two more nodes.”
Others also see a mixed picture in 2015. “In NAND, 3D spending is expected to be broader and larger, but it still lags planar spending until 2016. However, our customers are seeing diminishing gains from planar and (the) 3D adoption is inevitable. DRAM supply is expected to remain tight with strong potential for capacity additions,” said Gigi Lai, senior director of strategic marketing at Applied Materials. “Overall, we expect wafer fab equipment spending will be higher (in 2015), driven by the foundry finFET battle, broader investments in 3D NAND, and increasing DRAM spending.”
450mm and EUV
It’s safe to say that 450mm will not be a factor in 2015. In fact, the industry has put 450mm technology on hold for the foreseeable future. For now, 450mm is too expensive and the benefits are marginal.
But in 2015, the industry will keep a close eye on ASML’s ongoing efforts to put extreme ultraviolet (EUV) lithography into production. “If you look at the (recent) eBeam Initiative [] survey, it indicates that there is a little bit of an increase in the skepticism in EUV,” said Aki Fujimura, chairman and chief executive of D2S. “The survey echoes the statements from many in the industry: ‘We still want (EUV) to happen.’ But publicly, everyone is saying: ‘I don’t know if we can count on it. So we better have backup plans in place.’ “
Barring a major breakthrough in EUV, chipmakers will use 193nm immersion and multiple patterning for both 16nm/14nm and 10nm. “It’s not the question whether you can do (multiple patterning). Technically, it is possible. The question is if it’s economically viable. Certainly, the economic viability answer is very different, depending on who you are,” Fujimura said.
Backend blues
For years, meanwhile, the industry has been talking about the development of 2.5D and 3D chips using through-silicon vias (TSVs). So far, though, 2.5D/3D technology is taking longer than expected amid a number of cost and technical challenges. “We have stuff in production today. But again, these are high-performance applications,” said Jan Vardaman, president of TechSearch International. “Besides Xilinx, there are other people that are developing products using an interposer that should come out in 2015.”
So when will 2.5D/3D stacked die hit the mainstream? “These are new architectures,” Vardaman said. “New architectures take a long time to develop and you have to sort them out carefully.”
The ATE industry, meanwhile, is expected to grow by 20% in 2014. That was driven by booming demand for test in the mobile-based application processor space. Not long ago, Pacific Crest Securities projected that the ATE market would grow by 10% in 2015. But the firm recently lowered its forecast and now projects a 2% decline for ATE in 2015.

Friday, December 5, 2014

Apple Ask Samsung for iPhone 6 Parts

The flash memory bug of TLC performance versus MLC leads Apple to fix the memory IC controller and move from MLC to TLC NAND. It takes about a year to implement such changes. In the meantime, Apple looks to Samsung to provide MLC NAND (see the article below).


This is just another example of the limitations that the consolidation of semiconductor fabrication companies cause on their customers such as Apple. More about semiconductor industry consolidation from March 2012 Moore's Law Slowwwing and from February 2013 Semiconductor Moore's Law Running out of Money.

Ron

Insightful, timely, and accurate semiconductor consulting.Semiconductor information and news at - http://www.maltiel-consulting.com/


Samsung to Provide Parts for Apple’s iPhone 6 and 6 Plus in Order to Fix Huge Bug

Samsung to Provide Parts for Apples iPhone 6 and 6 Plus in Order to Fix Huge Bug Apple iPhone 6 and iPhone 6 Plus 300x225Samsung and Apple have been at war with each other for a long time due to a legal issue where the American tech giant sued Samsung for copying its iPad design. The trial turned out well in the end for Samsung, who continued to heavily criticize Apple and taunt the iPhone 6 and the iPhone 6 Plus devices in their promos and video adverts.
Taking this into consideration, it comes off as a huge and ironic surprise that the South Korean tech company will be providing parts to Apple. Apparently, there have been some discussions between the two tech companies in order to obtain NAND flash memory chips, as Apple needs some supplies of the triple-level cell NAND flash used in the iPhone 6.
Samsung to Provide Parts for Apples iPhone 6 and 6 Plus in Order to Fix Huge Bug Samsung Apple iPhone 6 and iPhone 6 Plus 300x200The higher capacity iPhone 6 handsets are apparently experiencing constant crashes and reboots, and apparently it’s because of the TLC memory. Naturally, Apple has to fix affected devices as soon as possible, especially when you think about how much money people spend on them. Apple’s products have some of the steepest price tags in the tech industry, but the quality has been heavily degrading over the years, making it look like Apple has no quality control. Besides supplying parts for Apple, Samsung will be making batteries for the iPhone 6 as well, according to Business Korea. This has been happening for a while, but Apple has been trying to reduce its reliance on Samsung components for its devices.
It seems that the two companies are going to bury the hatchet, but this could be strictly business-related, so we’ll have to wait and see.

Thursday, December 4, 2014

3D Flash Race:Intel vs Samsung

Following Samsung development of V- NAND Intel introduce their version of 3D NAND (see below). One of the benefits of 3D flash memories is the capability of using larger design rules such as 30-40 nm instead of scaling the design rules to smaller than 20nm.

One of the key problem of shrinking to smaller design rules than 20nm is the cost and complexity of multi-patterning photolithography and EUV lithography difficulties (ASML: Next-gen chipmaking tool ready forproduction in 2016 ). In addition, the reliability of the flash memory degrades when the memory cells become too close to each other.

"Samsung consciously went from a 24-layer 128Gbit MLC die to a 32-layer 86Gbit MLC die. In other words, Samsung could have upped the die capacity to ~170Gbit by just adding the extra layers, but the company chose to go with a smaller die instead. Smaller capacity dies have advantages in performance (higher parallelism) and applicability because eMMC/microSD devices have very strict die size constraints, "

Samsung only use 24 layers in fabricating the chips in order to increase the yield, which reduces the cost of working dies on each wafer. Adding layers that has to be manufactured with precise alignment and low defect density lengthen the learning curve of fabricating working dies. Intel is trying to catch up with Samsung which is already making the second generation of 3D NAND (Samsung 3D Process Pioneers Next Gen Semiconductor Devices ).


Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com/


Intel's 3D NAND to Ship in H2'15: 256Gbit Die

 & 32 Layers

by Kristian Vättö on November 25, 2014 5:20 AM EST
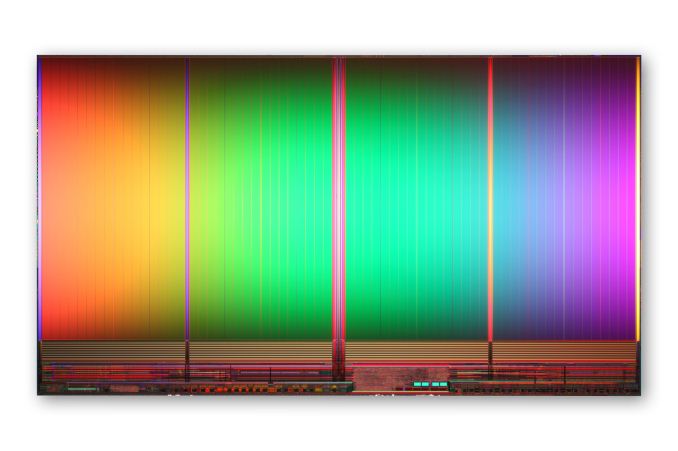
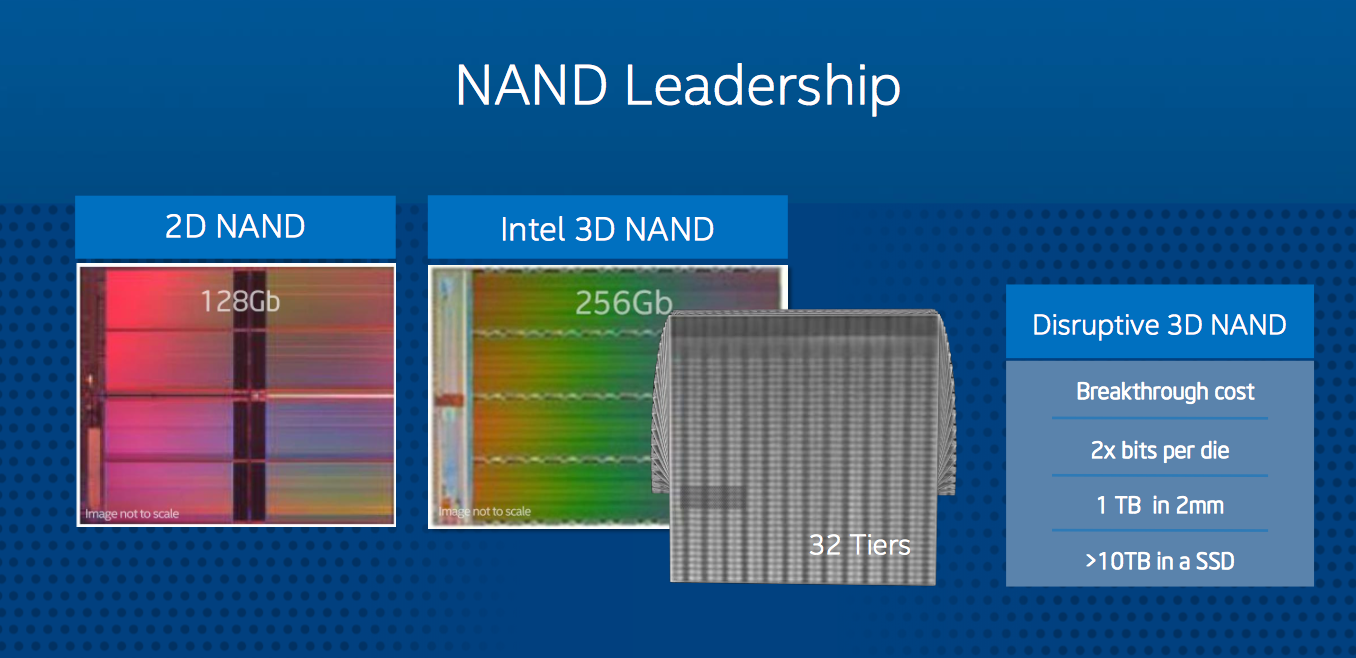
Last Thursday in its annual Investor Meeting Intel revealed the first details of its 3D NAND technology and announced that it will begin the shipments of 3D NAND in the second half of 2015. While Intel's investment in 3D NAND hasn't been a secret, the company has been relatively quiet about any specifics and the vital specs such as the number of layers and die capacity have remained unknown. In Thursday's webcast, Rob Crooke, Senior VP and General Manager of Intel's non-volatile memory group, disclosed that Intel's first generation 3D MLC NAND die will be 256Gbit (32GB) in capacity and will consist of 32 layers. The technology also enables a 384Gbit (48GB) TLC (3-bit-per-cell) die as we have learned over the years.
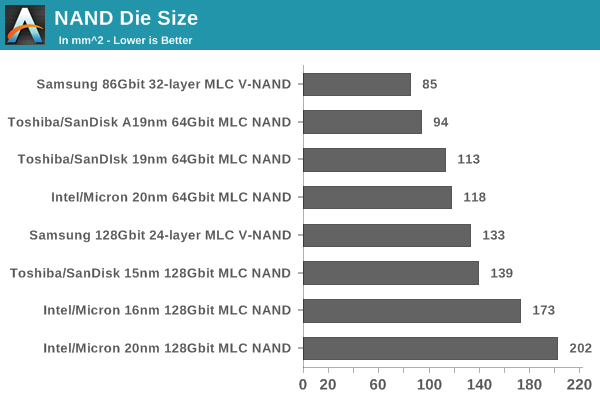
Intel claims that its 3D NAND is the most cost effective on the market and bases this on the fact that its die is 256Gbit whereas Samsung's is only up to 128Gbit at the moment. I'm not sure if I buy Intel's claim because while it's true that a higher capacity die results in higher array efficiency (i.e. peripheral circuitry takes less area), Samsung consciously went from a 24-layer 128Gbit MLC die to a 32-layer 86Gbit MLC die. In other words, Samsung could have upped the die capacity to ~170Gbit by just adding the extra layers, but the company chose to go with a smaller die instead. Smaller capacity dies have advantages in performance (higher parallelism) and applicability because eMMC/microSD devices have very strict die size constraints, so that might be a part of the reason why Samsung's strategy is so different from Intel's and Micron's. 
NAND Die Size
As the graph above shows, Intel's/Micron's NAND dies have historically been larger than the competitors', so the die capacity alone isn't enough to dictate whether Intel's 3D NAND is more cost efficient than Samsung, especially because both have 32 layers. Unlike Samsung, Intel didn't reveal the lithography that is used to manufacture the 3D NAND, but I would say it's safe to assume that the lithography is in the order of 30nm or 40nm because the whole idea of 3D NAND is to move away from multi-patterning to cut costs and with today's technology the smallest pitch of single-patterning is somewhere between 30nm and 40nm. Either way, it will be very interesting to see how Intel's 3D NAND stacks up against Samsung's because there are also some structural differences that affect the production cost as well as performance and endurance, but I'll save the structural analysis for a future article.
Intel said that 3D NAND technology will enable +10TB SSDs in the 'next couple of years', but it wasn't clear whether that is with first generation 3D NAND or some later generation with more layers and higher die capacity. Currently Intel's lineup tops out at 2TB (P3700 & P3600) with a 128Gbit die, so the 256Gbit die alone isn't enough to bring the capacities above 10TB. With effective controller development it should certainly be possible to build a 10TB SSD with a 256Gbit die, although I'm still inclined to believe that Mr. Crooke was referring to second or third generation 3D NAND with his statement. 
Similar to Intel's previous NAND efforts, 3D NAND has been jointly developed with Micron and will most likely be manufactured in the co-owned Utah plant as Intel sold its share in other fabs a couple of years ago. Interestingly enough, Mr. Crooke said that they also have the ability to bring 3D NAND production to an Intel fab, although to me that sounded more like a statement of technological possibility rather than a hint of future strategy. I wouldn't rule it out, though, but like Mr. Crooke said in the Q&A, Intel needs to have significant competitive advantage for it to make sense. In the past Intel's NAND technologies have generally been slightly ahead of the rest of the industry, but at least as of now Intel doesn't seem to have any substantial advantage in 3D NAND technology as Samsung is already shipping a 32-layer die and will likely ship a 48-layer die before Intel ships its 32-layer product.
All in all, we'll likely get more crumbs of information as the second half of 2015 gets closer. Given Intel's recent SSD strategy, I expect 3D NAND to first find its way to enterprise-class SSDs, but we'll see soon enough.

Wednesday, November 19, 2014

China Cell Phone Growth in 2014-5

The growth of NAND flash consumption in China is a strong indication of cell phone, tablet, and other mobile products future growth in China. The prediction in the article below of

"The proportion of China's overall NAND Flash usage relative to the world's NAND Flash output... expected to hit 20.6 per cent in 2014, and 30 per cent or more in 2015."


This prediction will depend on a very high growth in mobile products


Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com/


Mobile device space lifts memory market in China

Posted: 18 Nov 2014  
China has consumed about 4.789 billion DRAM chips and 3.518 billion NAND Flash chips from the 2Gb category this year, accounting for a respective 19.2 per cent and 20.6 per cent of the world's total DRAM and NAND Flash output. This highlights the country's increasing business potential as a result of the appeal China generates in terms of consumer device markets such as PC, smartphone and tablets, indicated DRAMeXchange, a research arm of TrendForce.
China's PC DRAM consumption is presently at about 15 per cent. Benefiting from domestic demand, Lenovo has managed to raise the scale of its business operations over the years, and is acquiring other companies as a means to boost its presence among first tier manufacturers. While the company is still competing fiercely with HP for top position in the PC market, its overall PC shipments are ahead of all of its other competitors. For 2015, DRAMeXchange predicted that Lenovo's market share will arrive at about 17 per cent. As has been the case with the other markets, mobile DRAM is expected to gradually replace PC DRAM as the mainstream in China given the country's growing smartphone and tablet sales. Aside from ZTE and Huawei, which are doing relatively well overseas, most China-based smartphone brands are expected to place their focus on the domestic market. Based on TrendForce's 2014 market statistics, China alone accounts for 28 per cent of mobile DRAM's overall bit demand. The importance of China's economic development to the entire DRAM industry is expected to become more apparent next year as that proportion rises to over 40 per cent.
As the NAND Flash manufacturing processes are advancing to under 1ynm, many NAND Flash applications including smartphone and tablet-based eMMCs and notebook-based SSDs are showing improved growth in the market. Competition among global OEM manufacturers, meanwhile, is starting to become more intense, with brands other than Apple and Samsung starting to make their way into the country's lucrative market. The level of China's NAND Flash consumption has managed to grow considerably over recent years due to Lenovo's rise to prominence, the above-average growth shown by China's emerging brands, and the improving standards of China's hardware designs. By the end of 2014, DRAMeXchange projects that the NAND Flash market's total value in China will reach up to $6.3 billion. The proportion of China's overall NAND Flash usage relative to the world's NAND Flash output, on the other hand, is expected to hit 20.6 per cent in 2014, and 30 per cent or more in 2015.

China's efforts over the years to transform from a manufacturing-based to consumption-based economy has been largely successful. Given the consistent growth in its economy and the country's rising wage levels, many of the productions in China are bound to be outsourced to other emerging countries. The Chinese government's present goal is to improve the country's outlook by implementing strategic policies that are aimed at enhancing its industrial capabilities. One such policy involves increasing the imports of semiconductor components such as smartphone CPU, AP, DRAM and NAND Flash, the combined value of which exceeds the value of China's imports for oil. In the future, it would be interesting to see whether Unisplendour Corp. Ltd's (UNIS) efforts to integrate resources from Spreadtrum Communications, RDA and Intel will be successful.
Due to the relatively high proportion of CPU, DRAM and NAND Flash components imported by China, the government policies that are implemented with regard to these three product categories may prove critical to the country's industries. A few days ago, the Chinese government announced a policy worth nearly $20 billion that involves mastering the technologies at the upper streams of the country's semiconductor supply chain and applying these technologies to mid to lower streams. The main purpose behind this is to enable the country's supply chains to be more integrated and to allow momentum in China's domestic industries to persist.

Wednesday, November 12, 2014

Samsung 3D Process Pioneers Next Gen Semiconductor Devices

Samsung is leading the semiconductor industry with a two year leads in development of 3D NAND (see the article below).


The basic 3D process could be applied to other technologies beside flash such as DRAM memory or logic. It enable increasing the number of the transistors on each dies without the need to shrink the design rules below 20nm.

It is a key advantages since you do not need to develop the very difficult EUV photolitography.

More about 3D NAND in August 2013 blog - Samsung’s 1Tb SSD: 3D Vertical NAND

It make sense for Samsung to apply 3D Flash first to enterprise SSD, where the growth rate is +40%.

See also Applied Materials development work on advance patterning  - Applied Materials Develops Advanced Patterning Solution for Memory Devices


Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com/


samsung_hwaseong_2optimized.jpg

An aerial view of Samsung's Hwaseong plant.
10 NOVEMBER 2014
Samsung Electronics is working to strengthen its position in the SSD market by increasing the profitability of its semiconductor memory business.
According to industry sources on Nov. 9, Samsung established a strategy to choose 3-bit V-NAND-based SSD as a new growth engine of its semiconductor memory business.
Since the productivity of 3-bit V-NAND is twice as high as 10 nm class planar NAND flash, the V-NAND is superior in price competitiveness, data processing speed, durability, and power efficiency. Thus, if the 3-bit V-NAND is featured in SSDs, it will increase the performance and price competitiveness of SSDs.
After its success in having a system to mass produce 3-bit V-NAND at the company's semiconductor plant in Hwaseong City near Seoul early last month, the Korean chip maker started to prepare for mass production at its 3D V-NAND production facility in Xian, China.
Considering that it normally takes six months to expand a mass production system to other plants, the industry anticipates that 3-bit V-NAND will be mass produced starting in May or April of next year.
The semiconductor plant in Hwaseong City produces mainly planar NAND flash for mobile devices, and thus it manufactures less than 100,000 V-NAND 300 mm wafers per month.
In contrast, the 3D V-NAND production facility in Xian, which commenced full operations in May, manufactures 300,000 to 400,000 sheets each month. However, the facility is considered to have capacity to produce more than 700,000 sheets.
Samsung aims to strengthen its dominant position in the market by increasing its share in the SSD market through the use of 3-bit V-NAND in SSDs.
The Korean company revealed that it will feature 3-bit V-NAND in SSDs starting next year at a conference call, following its announcement of results for the third quarter at the end of October.
Samsung's decision can be interpreted to mean that it intends to widen the gap with its rival companies in the global market by featuring 3-bit V-NAND in SSDs used in a data center environment and SSDs for PCs.
Market research firm IHS Technology recently reported that the world's largest memory chip maker will record US$3.277 billion in sales from SSDs in 2014, a 60 percent year-on-year gain. Its market share is expected to increase from 26 percent to 29 percent this year, which will put the firm in the top spot, followed by Sandisk with a 19 percent share, Intel (18 percent), Toshiba (9 percent), and Micron Technology (8 percent).
Currently, Samsung is the only company in the world that produces 3D V-NAND flash memory chips. The gap with rival companies in technology is generally acknowledged to be more than two years.
- See more at: http://www.businesskorea.co.kr/article/7217/focusing-ssds-samsung-mass-produce-3-bit-3d-nand-flash-ssd#sthash.vOPJFbm8.dpuf

Tuesday, November 11, 2014

TSMC, MediaTek and Hynix,Sales >20% in 2014

IC Insights report on top 20 Semiconductor sale leaders below. TSMC is benefiting from manufacturing A7 for Apple iPhone.

MediaTek from low price smart phones and its merge with MStar. More about MediaTek in January 2013 blog Apples' Cook in China (MediaTek Impact) .

Hynix maybe is benefiting from it recovery from last year Fab fire.

As usually SanDisk is not included in this IC Insights which already had $5.66B sales in 2011. More about SanDisk in earlier blog Top 25 2011 Semiconductor Sales Ranking


Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com


Nine of the Top 20 Semiconductor Suppliers are Forecast to Register Double-Digit Growth in 2014!


TSMC, MediaTek, and SK Hynix’s sales are each expected to jump by >20% this year.

Later this month, IC Insights’ November Update to The 2014 McClean Report will show a forecast ranking of the 2014 top 25 semiconductor suppliers with the companies’ sales broken down on a quarterly basis.  A preview of the forecast for the top 20 companies’ total 2014 sales results is presented in Figure 1.  The top 20 worldwide semiconductor (IC and O S D—optoelectronic, sensor, and discrete) sales ranking for 2014 includes eight suppliers headquartered in the U.S., three in Japan, three in Europe, three in Taiwan, two in South Korea, and one in Singapore, a relatively broad representation of geographic regions.

This year’s top-20 ranking includes two pure-play foundries (TSMC and UMC) and six fabless companies.  Pure-play IC foundry GlobalFoundries is forecast to be replaced in this year’s top 20 ranking by fabless IC supplier Nvidia.  It is interesting to note that the top four semiconductor suppliers all have different business models.  Intel is essentially a pure-play IDM, Samsung a vertically integrated IC supplier, TSMC a pure-play foundry, and Qualcomm a fabless company.

IC foundries are included in the top 20 ranking because IC Insights has always viewed the ranking as a top supplier list, not as a marketshare ranking, and realizes that in some cases semiconductor sales are double counted.  With many of our clients being vendors to the semiconductor industry (supplying equipment, chemicals, gases, etc.), excluding large IC manufacturers like the foundries would leave significant “holes” in the list of top semiconductor suppliers.  Foundries and fabless companies are clearly identified in Figure 1.  In the April Update to The McClean Report, marketshare rankings of IC suppliers by product type were presented and foundries were excluded from these listings.

As shown, it is expected to require total semiconductor sales of over $4.2 billion to make the 2014 top 20 ranking. In total, the top 20 semiconductor companies’ sales are forecast to increase by 9% this year as compared to 2013. However, when excluding the two pure-play foundries (TSMC and UMC) from the ranking, the top “18” semiconductor companies’ sales are forecast to increase by 8% this year, the same rate as IC Insights’ current forecast for total 2014 worldwide semiconductor market growth.


Figure 1
Outside of the top six spots, there are numerous changes expected within the 2014 top-20 semiconductor supplier ranking.  In fact, of the 14 companies ranked 7th through 20th, 10 of them are forecast to change positions in 2014 as compared with 2013 (with NXP expected to jump up two spots).


Wednesday, November 5, 2014

iPhone A8, A9 - Samsung or TSMC

It would make sense economically and to secure their supply for Apple to manufacture chips both in Samsung and TSMC. see iPhone A8, A9 and Second Sources.


Ron
Insightful, timely, and accurate semiconductor consulting.
Semiconductor information and news at - http://www.maltiel-consulting.com

Samsung and TSMC Reportedly Still Competing for Rights to Produce Apple's A9 Chip

Tuesday November 4, 2014 1:57 AM PST by Richard Padilla

Samsung and Taiwan Semiconductor Manufacturing Company (TSMC) are still competing for the rights to produce Apple's next-generation A9 chip as a primary supplier is expected to be named by the end of this year, reports Digitimes.


According to the report, Samsung has offered Apple lower pricing quotes in an attempt to secure the rights to produce the A9. The company is also willing to produce other chips like flash memory and perform optimization services in-house. Samsung was the longtime producer of Apple's A-series chips until Apple struck a deal with TSMC to produce its chips last year.

Last month, Samsung semiconductor head Kim Ki-nam announced that the company would begin work on 14-nanometer processors for Apple, indicating that the Korean company may have already won the bid to produce the next-generation A9 chip. However, it is also possible that both companies could share the production load as Apple looks to diversify its supply chain even further to better fit its production needs.

Last year, it was reported that Apple signed a contract with Samsung to handle 30% to 40% of total A9 chip production, as TSMC would be handling the rest of the production load. Apple's A9 chip would presumably be featured in next year's line of iPhones and iPads, as the iPhone 6 and 6 Plus currently use the 20-nanometer A8 processor. The iPad Air 2 uses a more powerful triple-core A8X chip which is up to 55% faster than the A8 chip found in the iPhone 6.